Why Coloured Gemstones Are the New Luxury Asset彩宝迎来价值重估
At the jewellery auctions of Geneva and Hong Kong in 2026, a quiet shift is taking place. The most decisive bidders are no longer only silver-haired collectors in tailored suits; increasingly, they are faces in their early thirties, chasing pigeon's-blood rubies, royal-blue sapphires and vivid-green emeralds. The coloured stones once dismissed as 'supporting actors' are completing a visible revaluation — and the pace is accelerating.
The starting point is scarcity. Gemfields, the mining-to-market giant, has seen its ruby auctions clear at record levels, while Christie's opened the year with a public warning that demand for fine coloured gemstones is surging beyond expectations. Core producing regions — Myanmar, Sri Lanka, Zambia — face geological and geopolitical headwinds that have tightened supply. Raw material prices are up more than 30% year-on-year, and the finest stones have doubled. With supply cut and demand rising, top-tier coloured gems have entered a self-reinforcing loop: the more they cost, the more people want them, and the scarcer they become.

What makes this cycle different is a structural migration of demand. The natural diamond, which anchored fine jewellery for decades, is under pressure from lab-grown alternatives; its share of the market has slipped from roughly 70% to 55% and is still falling. Younger buyers are rewriting the script. They are less attached to the old diamond hierarchy and more receptive to expressive colour and narrative. Rubies, sapphires and emeralds — the 'Big Three' — together with connoisseur stones such as Paraíba tourmaline, spinel and alexandrite, have stepped into the space diamonds vacated.
Allocation logic is also reshaping value. According to the Bain & Hurun 2025–2026 Wealth Report, the proportion of global high-net-worth wealth allocated to jewellery and coloured gemstones has climbed from 3% three years ago to 8% today — one of the fastest-growing alternative asset classes — even as allocations to property and public equities eased. Small, dense in value, and rich in cultural premium, coloured gems are increasingly treated as 'wearable safe-haven assets,' quietly entering the lists of family offices and private collectors.
The sales floor tells the same story of 'colour confidence.' Platform data from Nivoda for Q2 2026 shows sapphires accounting for nearly half (49.38%) of all gemstone sales, with blue the clear favourite; green and teal tones hold a steady quarter of demand, while pink continues to gain ground as retailers hunt for distinctive, design-led options. The oval cut leads at 39.62%, while the cushion cut climbed from 6.27% in Q1 to 9.35% — evidence that jewellers are broadening their cut mix beyond the classics. Most telling is the move up in carat weight: the 3–5ct and 5ct-plus bands together rose from about a fifth of sales value in Q1 to over a quarter in Q2. Buyers are trading up to larger, statement-led centre stones.
Upstream auctions underwrite that confidence. Gemfields' emerald sales have posted totals around USD 32 million with 100% sell-through and an average near USD 160 per carat; Zambian emeralds are up 25%–30% in recent years, untreated tsavorite and single blue sapphires above 3 carats have gained more than 50% since the pandemic, and exceptional Mahenge spinel has appreciated over 150%. Mozambican Paraíba has moved from roughly USD 7,000 to USD 10,000–12,000 per carat for fine qualities. Today's buyers scrutinise five metrics — origin, treatment, carat, certificate and liquidity — the language of a mature asset market rather than a decorative one.
The retail side confirms the pivot. Damien Cody, chairman of the International Coloured Gemstone Association, notes that a key driver of the shift is retailers actively seeking more stable product lines with healthier margins as diamonds wobble. From Bangkok to Shenzhen, a growing cohort of independent brands places coloured stones at the heart of their collections. Small-carat, light-weight, everyday designs hit the Gen-Z sweet spot of 'affordable luxury' and self-reward — the very psychology behind China's booming 'yueji' (self-pleasing) consumption, where jewellery fairs in Hong Kong, Shenzhen and Bangkok report near-40% year-on-year growth in high-end booth transactions and a buyer base increasingly made up of private collectors and family offices.
Colour preferences in 2026 follow a dual trajectory. On one hand, high-saturation hues remain synonymous with prestige: pigeon-blood reds, intense emerald greens and vivid blues perform strongly at auction and in flagship houses because they offer instant, cross-cultural legibility. On the other, a contemporary palette is gaining momentum — mint greens, seafoam tones, teal sapphires and translucent watery blues that slot easily into daily wear while retaining a strong identity. This modern restraint, echoed in the renewed interest in Afghan tourmalines, signals a market mature enough to hold both spectacle and subtlety at once.
Transparency has become a core pillar of modern luxury. Gemfields builds trust through responsible mining and transparent auction pricing; GIA grading and emerging blockchain provenance turn 'verifiable origin' into a real, tradeable attribute. When a piece of jewellery can prove where it came from, its liquidity strengthens, and it edges closer to 'asset' than 'accessory.' Emerging wealth in India, the Middle East and China continues to support the category even against the drag of U.S. tariffs and broader uncertainty — a resilience the trade credits to individuality and traceability.
Dealer-level pricing tells the same story in granular detail. Bangkok-based KV Gems, which supplies top European and American houses, reports that a one-carat untreated, loupe-clean royal-blue sapphire that once traded near USD 3,000 now sells in the USD 4,000 to 5,000 range; replacement cost, not speculation, underpins the structure. Goods between 1 and 5 carats remain far more liquid than stones above 10 carats, where transactions are thinner. The paradox of 2026 is a softening middle: the USD 5,000 to 25,000 segment that once formed the backbone of the American market has cooled as living costs rise, yet the finest untreated material meets little resistance. Scarcity, not hype, is doing the pricing.
The great maisons have leaned in. As the natural-diamond pipeline contracts, high-jewellery houses from Cartier to Van Cleef & Arpels are threading more coloured stones through their flagship collections, reinforcing the category's luxury status. Even 'phenomenal stones' — star sapphires, cat's-eye chrysoberyl — are moving from collector curiosities into mainstream design narratives, a shift GIA's Gem News International has tracked across major fairs. For a new generation of buyers, a stone's story and optical drama matter as much as its carat weight.
Nowhere is the shift more visible than in China. Vogue Business reports that the country's luxury jewellery market grew 46% to roughly USD 7 billion between 2020 and 2025, a 7.1% compound annual rate, even as gold and silver costs climbed. Domestic labels — from century-old houses such as Chow Tai Fook and Lao Feng Xiang to the disruptive newcomer Laopu, which fuses 24-karat gold with traditional silhouettes — are capturing share as younger consumers embrace guochao, or 'China chic.' Within that wave, coloured and semi-precious stones offer the colour and individuality a gold-only repertoire cannot, making them the natural next frontier for a confident local buyer who wants both heritage and self-expression.
For collectors, the implication is practical. Treat acquisition like portfolio construction: diversify across the Big Three for liquidity and a connoisseur stone or two for upside; insist on recognised certificates from GIA, GRS or SSEF; favour sizes that stay tradable, roughly 1 to 5 carats; and keep provenance paperwork as carefully as the stone itself. A gem without documentation is a gem without a market. Condition, and the story attached to it, is what preserves value across decades — which is precisely why how a stone is stored and shown deserves real attention.
Sustainability has quietly become a buying driver, not a footnote. A generation that asks where its coffee and clothes come from asks the same of its jewellery. Responsible mining, fair labour and traceable supply chains — the standards Gemfields and like-minded producers publish — now shape both brand reputation and resale confidence. A stone with a clean, documented conscience does not just feel better to wear; it travels better through the secondary market, where the next owner will ask the same questions you did. Ethics, it turns out, is also liquidity.
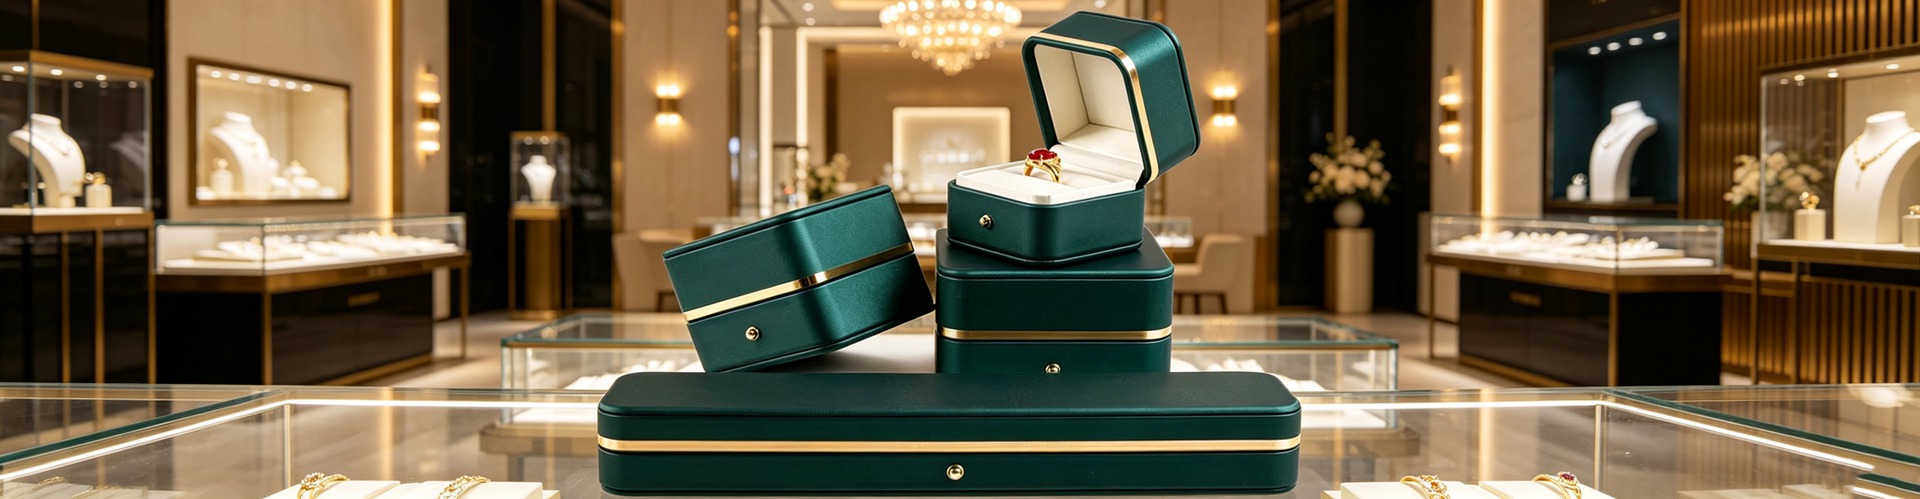
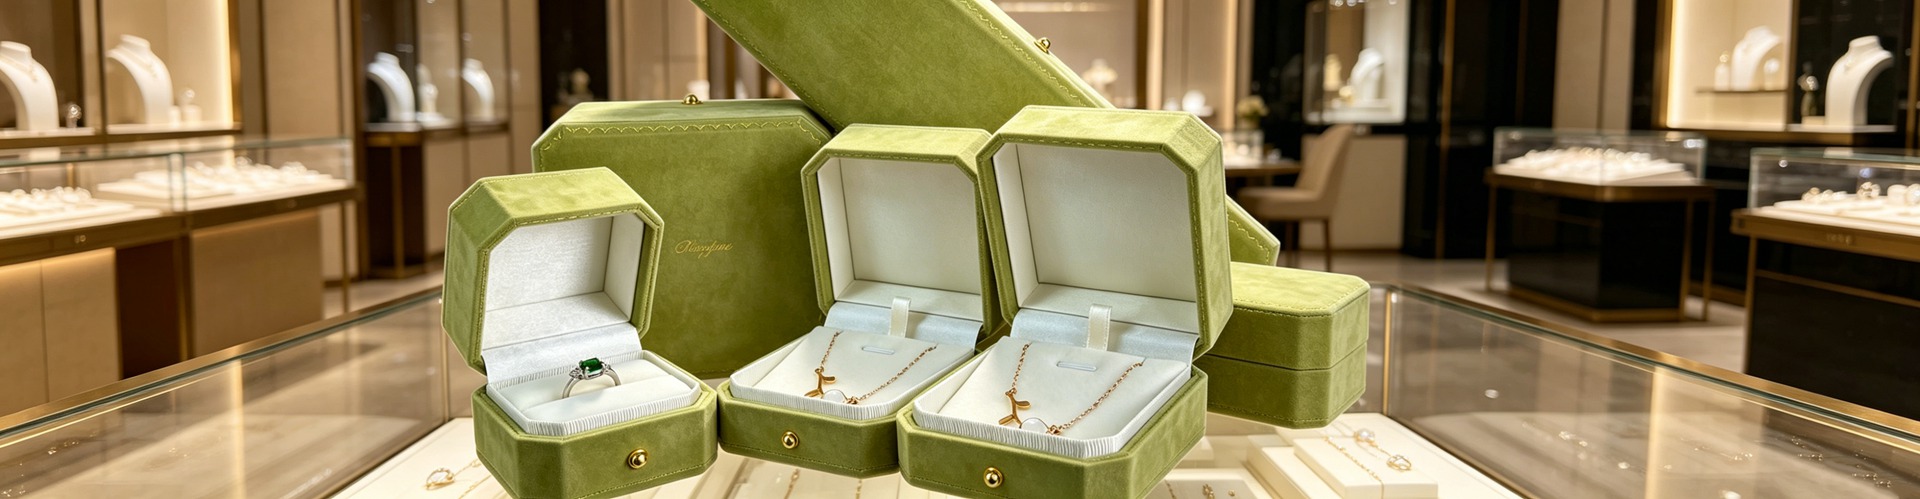
And when a gem carries both beauty and heirloom potential, how it is presented is no longer a footnote. A vivid-green emerald tossed into a drawer reveals none of its fire or story. Rest it instead inside a well-made jewelry box: the velvet slot cradles the metal, the lining's tone sets off the stone's depth, and the lid closes with a satisfying, deliberate resistance. That ritual is itself a confirmation of value. This is where jewelry packaging and display props earn their place — they do not compete for attention; they let the work speak. Specialist teams such as Shenzhen Junyimei exist precisely to give every stone worth keeping a presentation and protection worthy of it.
The golden age of coloured gemstones is not a one-way price rally. It is a collective revaluation built on scarcity, taste and trust. As young buyers pay for self-expression and collectors assess a centre stone with the rigor of asset allocation, what may be truly scarce is not the stone — but the care to store it well and present it beautifully.
This is original content. Copyright belongs to Shenzhen Junyimei.
Junyimei — present every jewel and timepiece at its best.2026年的珠宝圈,出现了一个耐人寻味的画面:在日内瓦与香港的拍场里,举牌最果断的不再是清一色西装革履的老藏家,而是一张张三十岁上下的年轻面孔。他们追逐的不是经典的白钻,而是鸽血红、皇家蓝、沃顿绿——那些曾被称作“小众配石”的彩色宝石,正在以肉眼可见的速度,完成一场价值重估。
这场重估的起点,是稀缺。国际宝石巨头Gemfields近年来的红宝石拍卖屡屡拍出天价,佳士得也在年初公开预警:高端彩色宝石的需求正在超预期激增。缅甸、斯里兰卡等核心产区受地质与政策影响,供给持续收缩,原料价格较去年同期上涨超过30%,高品质品种的涨幅甚至翻倍。当供给被腰斩、需求却逆势上扬,顶级彩宝自然进入了“越涨越买、越买越缺”的循环。
更有意味的是需求结构的迁移。过去数十年稳坐珠宝C位的天然钻石,正受到培育钻石的猛烈冲击——市场份额已从约70%滑落至55%,且仍在下降。年轻消费者的观念变了:他们不再为“一颗永流传”的钻石叙事买单,而是更愿意为能表达自我的颜色与故事付费。于是红宝石、蓝宝石、祖母绿这“三大经典”,连同帕拉伊巴碧玺、尖晶石、亚历山大石等小众品种,一起接过了天然钻石让出的位置。
资产配置的逻辑也在改写彩宝的身价。贝恩公司与胡润研究院联合发布的《2025—2026财富报告》显示,全球高净值人群在珠宝与彩色宝石上的配置比例,已从三年前的3%提升至8%,成为增速最快的另类资产之一;而同期房产与公开股票基金的配置比例则明显回落。体积小、价值密度高、文化溢价强——彩宝正以“可佩戴的避险资产”姿态,悄然进入家族办公室与私人藏家的清单。
销售端的数据同样印证了这股“色彩自信”。宝石交易平台Nivoda公布的2026年第二季度数据显示,蓝宝石已占其平台宝石销量的近一半(49.38%),蓝色依旧是最受欢迎的色调;椭圆切以39.62%的占比稳居第一,而垫形切则从一季度的6.27%攀升至9.35%,显示出买家正大胆尝试更丰富的切工。更关键的是克拉区间的上移:3—5克拉及5克拉以上大颗粒的销售额占比,从一季度约五分之一升至超过四分之一——人们正在“买大、买好、买主石”。
上游拍卖的坚挺,则为这场信心背书。Gemfields的祖母绿专拍曾录得3200万美元的总成交、100%的成交率,平均克拉价达160.78美元;赞比亚祖母绿近年涨价25%—30%,顶级马亨盖尖晶石涨幅更超过150%。买家不再只看“好不好看”,而是严格审视产地、有无优化、克拉大小、权威证书与流通性这五大指标——这恰恰是成熟资产市场的语言。
零售商端的变化同样醒目。国际有色宝石协会(ICA)主席Damien Cody指出,转向彩宝的一大动因,是零售商主动寻求更稳定的产品线——在钻石波动之际,彩宝提供了更可观的利润前景。从曼谷到深圳,越来越多的独立珠宝品牌把彩色宝石作为系列核心,小克拉、轻克重、可日常佩戴的设计款,正好击中了Z世代“悦己”与“可负担的奢侈”心理。香港、深圳、曼谷三地珠宝展的数据也显示,近两年高端宝石展位成交量同比增长近40%,私人藏家与家族办公室取代了部分传统零售商,成为新的主力买家。
与此同时,可追溯性成为现代奢侈品的核心要素。Gemfields以负责任开采与拍卖透明定价建立信任,GIA的宝石分级与新兴的区块链溯源,让“产地可信”变成可验证的资产属性。当一件珠宝能讲清自己从哪里来,它的流通性便更强,也就更接近“资产”而非“饰品”。
当一枚彩宝既承载审美,又兼具传承与流通属性,它的“呈现”便不再是一件小事。一颗沃顿绿的祖母绿,若随手丢进抽屉,它的火彩与故事无人领会;而当它静卧于一只质感妥帖的珠宝盒,绒布卡槽稳稳托住金属、内衬的色温衬出宝石的层次,开合的刹那带着恰到好处的阻尼——这种仪式感,本身就是对价值的一种确认。这正是珠宝包装设计与珠宝陈列道具的意义所在:它们不喧宾夺主,而是让作品自己开口说话。像深圳骏依美这样的专业团队,正是在为每一颗值得被珍藏的宝石,提供与之相称的呈现与呵护。
彩宝的黄金时代,从来不是价格的单边上扬,而是一场关于稀缺、审美与信任的集体重估。当年轻人愿意为“自我表达”持续买单,当藏家开始用资产配置的眼光审视一枚主石,真正稀缺的,或许不只是石头本身,更是懂得如何把它妥善收藏、好好呈现的那份用心。
本文为原创内容,版权归深圳骏依美所有,转载请注明出处。
骏依美——让每一件珠宝与腕表,都被更好地呈现。
The starting point is scarcity. Gemfields, the mining-to-market giant, has seen its ruby auctions clear at record levels, while Christie's opened the year with a public warning that demand for fine coloured gemstones is surging beyond expectations. Core producing regions — Myanmar, Sri Lanka, Zambia — face geological and geopolitical headwinds that have tightened supply. Raw material prices are up more than 30% year-on-year, and the finest stones have doubled. With supply cut and demand rising, top-tier coloured gems have entered a self-reinforcing loop: the more they cost, the more people want them, and the scarcer they become.
What makes this cycle different is a structural migration of demand. The natural diamond, which anchored fine jewellery for decades, is under pressure from lab-grown alternatives; its share of the market has slipped from roughly 70% to 55% and is still falling. Younger buyers are rewriting the script. They are less attached to the old diamond hierarchy and more receptive to expressive colour and narrative. Rubies, sapphires and emeralds — the 'Big Three' — together with connoisseur stones such as Paraíba tourmaline, spinel and alexandrite, have stepped into the space diamonds vacated.
Allocation logic is also reshaping value. According to the Bain & Hurun 2025–2026 Wealth Report, the proportion of global high-net-worth wealth allocated to jewellery and coloured gemstones has climbed from 3% three years ago to 8% today — one of the fastest-growing alternative asset classes — even as allocations to property and public equities eased. Small, dense in value, and rich in cultural premium, coloured gems are increasingly treated as 'wearable safe-haven assets,' quietly entering the lists of family offices and private collectors.
The sales floor tells the same story of 'colour confidence.' Platform data from Nivoda for Q2 2026 shows sapphires accounting for nearly half (49.38%) of all gemstone sales, with blue the clear favourite; green and teal tones hold a steady quarter of demand, while pink continues to gain ground as retailers hunt for distinctive, design-led options. The oval cut leads at 39.62%, while the cushion cut climbed from 6.27% in Q1 to 9.35% — evidence that jewellers are broadening their cut mix beyond the classics. Most telling is the move up in carat weight: the 3–5ct and 5ct-plus bands together rose from about a fifth of sales value in Q1 to over a quarter in Q2. Buyers are trading up to larger, statement-led centre stones.
Upstream auctions underwrite that confidence. Gemfields' emerald sales have posted totals around USD 32 million with 100% sell-through and an average near USD 160 per carat; Zambian emeralds are up 25%–30% in recent years, untreated tsavorite and single blue sapphires above 3 carats have gained more than 50% since the pandemic, and exceptional Mahenge spinel has appreciated over 150%. Mozambican Paraíba has moved from roughly USD 7,000 to USD 10,000–12,000 per carat for fine qualities. Today's buyers scrutinise five metrics — origin, treatment, carat, certificate and liquidity — the language of a mature asset market rather than a decorative one.
The retail side confirms the pivot. Damien Cody, chairman of the International Coloured Gemstone Association, notes that a key driver of the shift is retailers actively seeking more stable product lines with healthier margins as diamonds wobble. From Bangkok to Shenzhen, a growing cohort of independent brands places coloured stones at the heart of their collections. Small-carat, light-weight, everyday designs hit the Gen-Z sweet spot of 'affordable luxury' and self-reward — the very psychology behind China's booming 'yueji' (self-pleasing) consumption, where jewellery fairs in Hong Kong, Shenzhen and Bangkok report near-40% year-on-year growth in high-end booth transactions and a buyer base increasingly made up of private collectors and family offices.
Colour preferences in 2026 follow a dual trajectory. On one hand, high-saturation hues remain synonymous with prestige: pigeon-blood reds, intense emerald greens and vivid blues perform strongly at auction and in flagship houses because they offer instant, cross-cultural legibility. On the other, a contemporary palette is gaining momentum — mint greens, seafoam tones, teal sapphires and translucent watery blues that slot easily into daily wear while retaining a strong identity. This modern restraint, echoed in the renewed interest in Afghan tourmalines, signals a market mature enough to hold both spectacle and subtlety at once.
Transparency has become a core pillar of modern luxury. Gemfields builds trust through responsible mining and transparent auction pricing; GIA grading and emerging blockchain provenance turn 'verifiable origin' into a real, tradeable attribute. When a piece of jewellery can prove where it came from, its liquidity strengthens, and it edges closer to 'asset' than 'accessory.' Emerging wealth in India, the Middle East and China continues to support the category even against the drag of U.S. tariffs and broader uncertainty — a resilience the trade credits to individuality and traceability.
Dealer-level pricing tells the same story in granular detail. Bangkok-based KV Gems, which supplies top European and American houses, reports that a one-carat untreated, loupe-clean royal-blue sapphire that once traded near USD 3,000 now sells in the USD 4,000 to 5,000 range; replacement cost, not speculation, underpins the structure. Goods between 1 and 5 carats remain far more liquid than stones above 10 carats, where transactions are thinner. The paradox of 2026 is a softening middle: the USD 5,000 to 25,000 segment that once formed the backbone of the American market has cooled as living costs rise, yet the finest untreated material meets little resistance. Scarcity, not hype, is doing the pricing.
The great maisons have leaned in. As the natural-diamond pipeline contracts, high-jewellery houses from Cartier to Van Cleef & Arpels are threading more coloured stones through their flagship collections, reinforcing the category's luxury status. Even 'phenomenal stones' — star sapphires, cat's-eye chrysoberyl — are moving from collector curiosities into mainstream design narratives, a shift GIA's Gem News International has tracked across major fairs. For a new generation of buyers, a stone's story and optical drama matter as much as its carat weight.
Nowhere is the shift more visible than in China. Vogue Business reports that the country's luxury jewellery market grew 46% to roughly USD 7 billion between 2020 and 2025, a 7.1% compound annual rate, even as gold and silver costs climbed. Domestic labels — from century-old houses such as Chow Tai Fook and Lao Feng Xiang to the disruptive newcomer Laopu, which fuses 24-karat gold with traditional silhouettes — are capturing share as younger consumers embrace guochao, or 'China chic.' Within that wave, coloured and semi-precious stones offer the colour and individuality a gold-only repertoire cannot, making them the natural next frontier for a confident local buyer who wants both heritage and self-expression.
For collectors, the implication is practical. Treat acquisition like portfolio construction: diversify across the Big Three for liquidity and a connoisseur stone or two for upside; insist on recognised certificates from GIA, GRS or SSEF; favour sizes that stay tradable, roughly 1 to 5 carats; and keep provenance paperwork as carefully as the stone itself. A gem without documentation is a gem without a market. Condition, and the story attached to it, is what preserves value across decades — which is precisely why how a stone is stored and shown deserves real attention.
Sustainability has quietly become a buying driver, not a footnote. A generation that asks where its coffee and clothes come from asks the same of its jewellery. Responsible mining, fair labour and traceable supply chains — the standards Gemfields and like-minded producers publish — now shape both brand reputation and resale confidence. A stone with a clean, documented conscience does not just feel better to wear; it travels better through the secondary market, where the next owner will ask the same questions you did. Ethics, it turns out, is also liquidity.
And when a gem carries both beauty and heirloom potential, how it is presented is no longer a footnote. A vivid-green emerald tossed into a drawer reveals none of its fire or story. Rest it instead inside a well-made jewelry box: the velvet slot cradles the metal, the lining's tone sets off the stone's depth, and the lid closes with a satisfying, deliberate resistance. That ritual is itself a confirmation of value. This is where jewelry packaging and display props earn their place — they do not compete for attention; they let the work speak. Specialist teams such as Shenzhen Junyimei exist precisely to give every stone worth keeping a presentation and protection worthy of it.
The golden age of coloured gemstones is not a one-way price rally. It is a collective revaluation built on scarcity, taste and trust. As young buyers pay for self-expression and collectors assess a centre stone with the rigor of asset allocation, what may be truly scarce is not the stone — but the care to store it well and present it beautifully.
This is original content. Copyright belongs to Shenzhen Junyimei.
Junyimei — present every jewel and timepiece at its best.2026年的珠宝圈,出现了一个耐人寻味的画面:在日内瓦与香港的拍场里,举牌最果断的不再是清一色西装革履的老藏家,而是一张张三十岁上下的年轻面孔。他们追逐的不是经典的白钻,而是鸽血红、皇家蓝、沃顿绿——那些曾被称作“小众配石”的彩色宝石,正在以肉眼可见的速度,完成一场价值重估。
这场重估的起点,是稀缺。国际宝石巨头Gemfields近年来的红宝石拍卖屡屡拍出天价,佳士得也在年初公开预警:高端彩色宝石的需求正在超预期激增。缅甸、斯里兰卡等核心产区受地质与政策影响,供给持续收缩,原料价格较去年同期上涨超过30%,高品质品种的涨幅甚至翻倍。当供给被腰斩、需求却逆势上扬,顶级彩宝自然进入了“越涨越买、越买越缺”的循环。
更有意味的是需求结构的迁移。过去数十年稳坐珠宝C位的天然钻石,正受到培育钻石的猛烈冲击——市场份额已从约70%滑落至55%,且仍在下降。年轻消费者的观念变了:他们不再为“一颗永流传”的钻石叙事买单,而是更愿意为能表达自我的颜色与故事付费。于是红宝石、蓝宝石、祖母绿这“三大经典”,连同帕拉伊巴碧玺、尖晶石、亚历山大石等小众品种,一起接过了天然钻石让出的位置。
资产配置的逻辑也在改写彩宝的身价。贝恩公司与胡润研究院联合发布的《2025—2026财富报告》显示,全球高净值人群在珠宝与彩色宝石上的配置比例,已从三年前的3%提升至8%,成为增速最快的另类资产之一;而同期房产与公开股票基金的配置比例则明显回落。体积小、价值密度高、文化溢价强——彩宝正以“可佩戴的避险资产”姿态,悄然进入家族办公室与私人藏家的清单。
销售端的数据同样印证了这股“色彩自信”。宝石交易平台Nivoda公布的2026年第二季度数据显示,蓝宝石已占其平台宝石销量的近一半(49.38%),蓝色依旧是最受欢迎的色调;椭圆切以39.62%的占比稳居第一,而垫形切则从一季度的6.27%攀升至9.35%,显示出买家正大胆尝试更丰富的切工。更关键的是克拉区间的上移:3—5克拉及5克拉以上大颗粒的销售额占比,从一季度约五分之一升至超过四分之一——人们正在“买大、买好、买主石”。
上游拍卖的坚挺,则为这场信心背书。Gemfields的祖母绿专拍曾录得3200万美元的总成交、100%的成交率,平均克拉价达160.78美元;赞比亚祖母绿近年涨价25%—30%,顶级马亨盖尖晶石涨幅更超过150%。买家不再只看“好不好看”,而是严格审视产地、有无优化、克拉大小、权威证书与流通性这五大指标——这恰恰是成熟资产市场的语言。
零售商端的变化同样醒目。国际有色宝石协会(ICA)主席Damien Cody指出,转向彩宝的一大动因,是零售商主动寻求更稳定的产品线——在钻石波动之际,彩宝提供了更可观的利润前景。从曼谷到深圳,越来越多的独立珠宝品牌把彩色宝石作为系列核心,小克拉、轻克重、可日常佩戴的设计款,正好击中了Z世代“悦己”与“可负担的奢侈”心理。香港、深圳、曼谷三地珠宝展的数据也显示,近两年高端宝石展位成交量同比增长近40%,私人藏家与家族办公室取代了部分传统零售商,成为新的主力买家。
与此同时,可追溯性成为现代奢侈品的核心要素。Gemfields以负责任开采与拍卖透明定价建立信任,GIA的宝石分级与新兴的区块链溯源,让“产地可信”变成可验证的资产属性。当一件珠宝能讲清自己从哪里来,它的流通性便更强,也就更接近“资产”而非“饰品”。
当一枚彩宝既承载审美,又兼具传承与流通属性,它的“呈现”便不再是一件小事。一颗沃顿绿的祖母绿,若随手丢进抽屉,它的火彩与故事无人领会;而当它静卧于一只质感妥帖的珠宝盒,绒布卡槽稳稳托住金属、内衬的色温衬出宝石的层次,开合的刹那带着恰到好处的阻尼——这种仪式感,本身就是对价值的一种确认。这正是珠宝包装设计与珠宝陈列道具的意义所在:它们不喧宾夺主,而是让作品自己开口说话。像深圳骏依美这样的专业团队,正是在为每一颗值得被珍藏的宝石,提供与之相称的呈现与呵护。
彩宝的黄金时代,从来不是价格的单边上扬,而是一场关于稀缺、审美与信任的集体重估。当年轻人愿意为“自我表达”持续买单,当藏家开始用资产配置的眼光审视一枚主石,真正稀缺的,或许不只是石头本身,更是懂得如何把它妥善收藏、好好呈现的那份用心。
本文为原创内容,版权归深圳骏依美所有,转载请注明出处。
骏依美——让每一件珠宝与腕表,都被更好地呈现。